Musk Vs Mukesh: Why Starlink’s India Launch Hinges on Security Clearances Despite Having Licence

Elon Musk’s latest attack on Mukesh Ambani has brought a central question surrounding Starlink’s India expansion into focus: why does the satellite internet company remain unable to launch commercially despite securing a licence?

The SpaceX chief on Friday sarcastically addressed the Reliance Industries chairman as “Prime Minister Ambani” and accused him of wanting to preserve a monopoly in India’s internet market. His remarks followed a series of posts questioning the regulatory hurdles facing Starlink, which aims to provide connectivity in areas where conventional broadband infrastructure is difficult or expensive to deploy.

“Dear Prime Minister Ambani, Please accept my humble apologies for not realizing that you are the real boss of India,” Musk wrote on X.

He then questioned whether Ambani would allow Starlink to compete, alleging that established business interests were seeking to protect their position. Musk has not publicly substantiated his accusations against Ambani with evidence in the posts cited in the report.

The immediate issue, however, is regulatory rather than a confirmed confrontation between the two companies. Starlink has obtained a licence to provide satellite communication services in India, but security-related clearances and other approvals remain necessary before commercial operations can begin.

Security Requirements Remain a Key Hurdle

The Indian government has pushed back against Musk’s claims that Starlink is being blocked from entering the market. It has maintained that satellite communication operators must satisfy security requirements and comply with applicable regulations before they can offer services.

Officials have described allegations of discriminatory treatment as “baseless and misconceived”, stressing that security compliance is compulsory for every satellite communications licensee.

Musk, meanwhile, has said Starlink has spent five years complying with Indian laws and regulations. He previously accused unnamed “oligarchs” of trying to prevent the company from entering India, although he did not identify the alleged individuals or businesses in those initial remarks.

The distinction matters because a licence to provide satellite communications does not, by itself, establish that every requirement for a commercial launch has been fulfilled. The outstanding approvals remain the immediate obstacle identified in the available account of Starlink’s entry process.

Musk has argued that the service could bring internet access to communities that remain underserved by traditional networks. He said students could gain access to educational opportunities and small businesses could reach customers in international markets.

He has also highlighted Starlink’s role in restoring communications during natural disasters, when conventional systems fail. Those arguments form the public case for expanding satellite internet access, but they do not remove the need to satisfy India’s regulatory conditions.

India’s Telecom Market Faces a Potential New Competitor

Starlink’s eventual entry would add a satellite-based connectivity option to a market dominated by terrestrial mobile and broadband networks. Reliance Jio, led by Ambani, and Bharti Airtel are major players in the sector, while satellite services could offer an alternative in locations where fibre deployment or mobile coverage is limited.

The commercial implications will depend on Starlink’s service pricing, coverage, capacity and ability to attract customers. Satellite internet is not automatically a cheaper substitute for existing broadband, particularly in a price-sensitive market such as India.

Musk’s criticism also raises questions about the relationship between private competition and regulatory oversight. However, the public allegations do not establish that Ambani or Reliance has influenced the government’s decisions on Starlink’s approvals.

For now, Starlink’s commercial launch depends on completing the remaining regulatory process. Musk’s public campaign has intensified scrutiny of the delay, but the government’s stated position is that security and compliance requirements apply to all satellite communications providers.

The next substantive development will be whether Starlink receives the outstanding clearances and announces a commercial launch timeline for India.

Rupee Nears Record Low as RBI Intervention Counters Dollar, Oil Pressures

The Indian rupee edged higher on Friday as intervention by the Reserve Bank of India (RBI), a weaker US dollar and falling global crude oil prices helped slow its slide towards a record low. Persistent pressure from oil imports, foreign portfolio outflows and geopolitical uncertainty, however, continues to weigh on the currency.

The rupee rose 0.2% to ₹96.61 per US dollar on Friday, October 9, after the central bank intervened in the foreign exchange market around the ₹96.80 level to prevent the currency from approaching its previous record low of ₹96.96, reached in May, Reuters reported.

The recovery followed a difficult week for the currency after the RBI raised its benchmark repo rate by 25 basis points to 5.50% on Wednesday and shifted its policy stance from neutral to calibrated tightening. The rate increase was the first since February 2023.

The latest currency movement highlights the challenge facing the central bank: tighter monetary policy and foreign exchange intervention can help stabilise the rupee, but they cannot eliminate the external pressures driving demand for dollars.

RBI Intervention Buys Time as External Risks Persist

The RBI has maintained a presence in the currency market over recent sessions to limit the rupee’s depreciation. Traders cited intervention near ₹96.80 on Friday, while the softer dollar and lower US Treasury yields provided additional support.

A weaker dollar generally offers some relief to emerging-market currencies by reducing the cost of dollar-denominated obligations and easing pressure on capital flows. Falling US Treasury yields can also make dollar assets relatively less attractive, depending on the broader interest-rate outlook and investor risk appetite.

However, India’s currency remains vulnerable to sustained foreign portfolio outflows, elevated oil prices and uncertainty surrounding the conflict involving Iran.

The rupee has been among Asia’s weaker-performing currencies this year, reflecting the combined impact of global financial conditions and India’s exposure to energy-import costs. A fresh record low could also reinforce negative market sentiment and increase demand for hedging against further depreciation.

The RBI’s intervention is therefore aimed at limiting disorderly movements rather than guaranteeing a particular exchange rate. The sustainability of the rupee’s recovery will depend partly on whether external conditions improve and foreign exchange demand moderates.

Crude Oil and US-Iran Talks Remain Critical for Rupee

Oil prices are a central variable for India’s currency outlook. As one of the world’s largest crude importers, India needs substantial dollar payments to purchase energy from overseas suppliers. Higher crude prices can increase the import bill, widen the trade deficit and add to domestic inflationary pressure.

Brent crude fell about 1.5% on Friday after US President Donald Trump said Washington would not launch military action against Iran before the US midterm elections, citing progress in discussions aimed at ending the conflict.

The decline in oil prices, combined with a softer dollar and lower US Treasury yields, supported the rupee and other Asian currencies.

But the relief could prove temporary if negotiations stall, oil supplies are disrupted or global bond yields rise again. Any sustained increase in crude prices would complicate the RBI’s efforts to manage currency volatility while containing inflation.

For Indian households, a persistently weak rupee can raise the domestic cost of imported goods and overseas expenses, including foreign education and travel. Import-dependent businesses may also face higher input costs, while exporters and recipients of remittances in dollars can benefit from the conversion of foreign earnings into rupees.

The immediate focus for currency traders remains the RBI’s intervention, movements in the dollar and US Treasury yields, foreign investment flows and developments in the Middle East.

Friday’s gain offers the central bank some breathing room, but it does not yet establish a durable reversal in the rupee’s broader downward trend.

Oil prices fall as Trump rules out Iran attack before US elections

Oil prices fell on Friday after US President Donald Trump said Washington would not attack Iran before the November 3 midterm elections, easing fears of further disruptions to global energy supplies amid negotiations to end the conflict.

Brent crude futures fell $1.37, or 1.3%, to $102.91 a barrel by 0450 GMT, while US West Texas Intermediate (WTI) crude futures declined $1.09, or 1.2%, to $90.40, Reuters reported.

The decline followed a sharp rally on Thursday, when Brent settled about 4% higher as attacks on oil-shipping routes in the Middle East heightened concerns over supplies. Despite Friday’s retreat, Brent remained on course for a weekly gain, while WTI was headed for a slight weekly decline.

Trump said on Thursday that Washington was holding “productive discussions” with Tehran and that the United States would not launch an attack before the November elections. His comments followed reports that the administration had been considering military action against Iran.

The easing in prices reflects a shift in market expectations rather than a resolution of the conflict. Oil traders remain concerned about the security of shipments through the Strait of Hormuz, a critical route for global energy supplies.

Strait of Hormuz remains a major supply risk

Iran’s Tasnim news agency reported that Foreign Minister Abbas Araqchi said Tehran was reviewing the US response to an Iranian proposal to reopen the Strait of Hormuz within seven days.

Before the war, the strategic waterway carried shipments equivalent to about 20% of global oil and fuel supplies. Increased threats to shipping in the Gulf and the strait have contributed to sharp price swings in recent weeks.

Any sustained improvement in negotiations and maritime security could ease pressure on crude prices. However, analysts have cautioned that diplomatic statements alone are insufficient to guarantee a recovery in energy flows.

“The prospect of easing tensions still needs to be reinforced by concrete progress in negotiations and improvements in shipping safety through the Strait of Hormuz,” said Linh Tran, an analyst at XS.com.

Washington is continuing economic pressure on Tehran despite the diplomatic activity. The United States imposed fresh sanctions on Thursday targeting individuals, networks and 17 vessels accused of transporting Iranian crude oil, petroleum products and petrochemicals.

The combination of negotiations, sanctions and security threats has left markets sensitive to announcements from Washington and Tehran.

China fuel exports and US hurricane add to market uncertainty

Developments outside the Middle East are also influencing the outlook for energy prices.

China, the world’s largest oil importer, is expected to resume refined-fuel exports after a temporary halt during its Golden Week holiday. The move could ease tight supplies of diesel, gasoline and jet fuel in international markets.

The International Energy Agency has also agreed to accelerate the release of oil stocks under a plan launched in March, with priority given to diesel supplies.

Meanwhile, Hurricane Isaias is disrupting US oil production in the Gulf of Mexico. Producers had shut in about 1.3 million barrels per day, equivalent to 62.9% of current production in the affected area, as of Thursday, according to the US Marine Minerals Administration.

The disruption could support prices if production recovery is delayed, although the duration of the impact will depend on post-storm inspections and the speed at which facilities resume operations.

For India, a sustained decline in crude prices could ease the country’s import bill and reduce some inflationary pressure. However, Friday’s fall alone does not establish a lasting downward trend, particularly while Brent remains above $100 a barrel and geopolitical risks continue to threaten supplies.

The direction of prices will depend on whether US-Iran negotiations produce tangible progress, shipping through the Strait of Hormuz becomes safer and disrupted production and fuel exports recover.

For now, the market is balancing hopes of diplomatic de-escalation against continuing risks to global energy supplies.

RBI raises repo rate to 5.5% as inflation risks intensify

The Reserve Bank of India raised its benchmark repo rate by 25 basis points to 5.5% on Wednesday, its first increase since February 2023, as rising inflation risks, higher crude oil prices and global financial pressures prompted the central bank to shift towards tighter monetary policy.

The Monetary Policy Committee (MPC) unanimously raised the repo rate from 5.25% and changed its policy stance from neutral to “calibrated tightening”, signalling that the RBI is prepared to respond further if inflationary pressures continue to build.

The decision marks a significant change after a prolonged period in which the RBI had kept borrowing costs unchanged while supporting economic growth. The latest move comes as the economy remains relatively strong but faces a more difficult external environment, particularly from elevated oil prices, a weaker rupee and tighter global financial conditions.

The RBI’s decision also comes after retail inflation rose to 4.82% in August from 4.45% in July, moving further above the central bank’s 4% medium-term target. The combination of higher commodity prices and risks of broader price pressures has increased concerns that inflation could remain elevated in the coming quarters.

Inflation, oil prices force policy recalibration

Higher crude oil prices have emerged as one of the biggest risks to India’s inflation outlook. Brent crude has traded above $100 a barrel amid disruptions and uncertainty linked to the conflict involving Iran, raising concerns about India’s import bill and the cost of fuel, transport and other inputs.

The impact extends beyond fuel. Higher energy and commodity costs can raise production and transportation expenses for businesses and eventually feed into consumer prices.

The RBI has therefore faced a difficult policy trade-off. Keeping rates unchanged would continue to support borrowing and investment, but allowing inflation expectations to become entrenched could make it harder to bring inflation back towards the 4% target.

The central bank raised its FY27 inflation projection to 5.2%, from 5% previously, according to reports on the policy decision. The RBI is also reported to expect headline inflation to remain elevated in the near term before easing as some supply pressures moderate.

The shift to calibrated tightening gives the RBI greater flexibility to raise rates further if inflation remains persistent. At the same time, the language does not automatically commit the central bank to a prolonged series of increases, leaving future decisions dependent on incoming inflation, growth and financial-market data.

The rate increase could raise borrowing costs for households and businesses, particularly for loans linked to external benchmarks. Banks could pass on the increase through higher lending rates, potentially raising EMIs for home, vehicle and other floating-rate loans.

Deposit rates could also move higher as banks seek to attract funds, potentially benefiting savers.

Strong growth gives RBI room to focus on prices

The RBI’s decision comes despite continued strength in the domestic economy.

India’s economy expanded 7.8% in the June quarter, providing the central bank with greater room to prioritise price stability rather than maintaining exceptionally accommodative monetary conditions. The RBI has also raised its FY27 growth projection to 7.1% from 6.7%, according to reports following the policy announcement.

The stronger growth performance reduces the immediate risk that a moderate rate increase will cause a sharp slowdown.

However, the outlook is not without risks. Higher crude prices can simultaneously weaken growth and increase inflation by raising input costs and reducing consumers’ purchasing power.

Global financial conditions are another concern. US Treasury yields have risen sharply, while the dollar has remained firm, putting pressure on emerging-market currencies.

The rupee fell to around 96.42 against the dollar on Tuesday, a two-month low, as foreign investors continued to withdraw money from Indian equities and oil prices remained elevated.

A weaker rupee makes imported goods and commodities more expensive, adding another channel through which global price pressures can reach the Indian economy.

Liquidity, rupee remain key policy challenges

The RBI’s policy response is not limited to the repo rate. Managing excess liquidity in the banking system has become an increasingly important part of monetary policy.

System liquidity had surged earlier in September, prompting the RBI to use tools including open market operations, variable-rate reverse repo operations and foreign-exchange transactions to absorb excess funds.

Liquidity surplus had fallen substantially from the levels seen earlier in September, although the banking system continued to carry a sizeable surplus. According to recent data cited ahead of the policy decision, the liquidity surplus stood at around Rs 5 lakh crore on October 6.

The RBI’s challenge is to prevent surplus liquidity from weakening the transmission of tighter monetary policy while avoiding excessive tightening that could disrupt credit conditions.

The central bank has also been using foreign-exchange operations to manage volatility in the rupee. Reuters reported that the RBI has deployed dollar-rupee swaps, bond sales and other tools while dealing with excess liquidity and currency pressures.

The currency remains particularly vulnerable because India is heavily dependent on imported crude oil. A sustained rise in oil prices can widen the trade deficit, increase demand for dollars and put additional pressure on the rupee.

Markets look for signals on further rate hikes

For financial markets, the 25-basis-point increase itself was largely anticipated. The bigger question is how far the RBI is prepared to go if inflation remains above target.

The shift to calibrated tightening suggests that the central bank is no longer treating the current inflation increase as a temporary development that can simply be ignored while growth remains strong.

Market participants will therefore closely watch the RBI’s assessment of core inflation, crude prices, the rupee, global bond yields and domestic demand.

A prolonged tightening cycle could raise borrowing costs for companies and households and eventually slow credit growth. Banks could benefit from higher lending yields initially, but a sustained increase in funding costs could pressure margins and loan demand.

Government bond yields are also likely to remain sensitive to expectations about the future rate path. Higher rates can increase the cost of government borrowing and influence valuations across debt and equity markets.

For the equity market, the policy creates a more complicated environment. Strong economic growth remains supportive for corporate earnings, but higher interest rates, elevated oil prices, foreign outflows and currency weakness could limit the upside.

The RBI’s immediate task is therefore to prevent a supply-driven inflation shock from becoming entrenched while preserving the underlying momentum in the economy.

The first rate increase in more than three years marks a clear change in policy direction. Whether it develops into a sustained tightening cycle will depend largely on the trajectory of inflation, oil prices and the rupee in the months ahead.

US Goods Trade Deficit with India Reaches $6.2 Billion in August; Implications Ahead

The United States recorded a $6.2 billion goods trade deficit with India in August, as America’s overall trade gap widened sharply during the month on a surge in imports, according to official data released Tuesday.

The India deficit was reported on a Census basis and covered merchandise trade only. The monthly figure does not represent the broader bilateral trade balance between the two countries, which also includes services.

India’s August deficit was the same as that recorded with Germany and was smaller than the US goods deficits with Mexico, Vietnam, Taiwan, China, the European Union, South Korea and Canada.

The data come as trade remains a major issue in US-India economic relations, with Washington seeking to reduce trade deficits with major trading partners.

US trade deficit widens to $105.6 billion

The US goods and services trade deficit rose to $105.6 billion in August, up $12.7 billion, or 13.7%, from a revised $92.8 billion in July.

Exports increased by $4.5 billion to $315.2 billion, while imports rose by $17.2 billion to $420.8 billion.

The increase in the overall deficit was driven primarily by a $12.8 billion expansion in the goods deficit, which reached $136.6 billion. The United States continued to post a sizeable services surplus, which edged up by less than $100 million to $31 billion.

Among the major trading partners, the largest US goods deficit was with Mexico at $27.7 billion, followed by Vietnam at $24 billion, Taiwan at $18.3 billion and China at $16.4 billion.

The US deficit with the European Union stood at $11 billion, while South Korea accounted for $9.4 billion and Canada $7.1 billion.

Malaysia followed India and Germany with a $6 billion deficit. The US also recorded goods deficits of $4.3 billion with Italy and $3.7 billion with Japan.

The United States ran goods trade surpluses with several major partners and regions, including the Netherlands at $7.7 billion, South and Central America at $5.6 billion, the United Kingdom at $3.6 billion and Hong Kong at $2.3 billion.

Imports surge as gold, oil and semiconductors rise

US goods exports increased by $4.4 billion to $205.7 billion in August, helped by higher shipments of industrial supplies and materials, including nonmonetary gold, crude oil and fuel oil.

Capital goods exports also increased, with semiconductor, computer and computer accessory shipments rising during the month. Pharmaceutical exports, however, fell by $2.4 billion.

Goods imports climbed $17.2 billion to $342.2 billion. Industrial supplies and materials accounted for a $9.1 billion increase, including higher imports of crude oil and nonmonetary gold.

Capital goods imports rose by $6.2 billion, with semiconductor imports increasing by $2.4 billion.

Despite the sharp monthly deterioration, the US trade deficit remained significantly lower during the first eight months of 2026 than in the same period last year.

The US goods and services deficit fell by $138.2 billion, or 19.9%, year-on-year, during the January-August period. Exports rose by $267.7 billion, or 11.8%, while imports increased by $129.5 billion, or 4.4%.

Implications for India

For India, the $6.2 billion US goods deficit is likely to keep trade imbalances high on Washington’s agenda, potentially increasing pressure on New Delhi to expand imports from the US or offer greater market access in sectors where American exporters see barriers.

However, the August figure alone does not indicate a deterioration in bilateral trade relations, as the broader balance also includes services, where India traditionally runs a surplus.

The key implications will depend on whether the US uses the persistent goods deficit to seek further tariff concessions, greater purchases of American energy and goods, or changes in India’s market-access policies.

Essar’s $18 Billion US Bet Raises a Bigger Question for India

Essar Group’s planned $18 billion investment in the US steel industry is a major overseas expansion, but its significance for India goes beyond the size of the cheque.

The project raises a basic economic question: why are large Indian business groups finding some of their biggest new industrial opportunities outside India at a time when the country is trying to trigger a broad private investment cycle?

Essar-backed Mesabi Metallics plans to build a $15 billion steel plant in Iowa, supplied by iron ore from its Minnesota mine. The first phase is expected to produce 7.5 million tonnes of steel annually, with capacity eventually rising to 10 million tonnes. Production is targeted for 2030. Essar has already invested more than $2.5 billion in the Minnesota operation, while the US Export-Import Bank has committed up to $10 billion in financing for its expansion.

This is not simply an Indian company moving an existing factory abroad. Essar is building an integrated US supply chain around American raw materials, American steel demand and American industrial policy.

That distinction matters. Indian companies routinely invest overseas to acquire technology, brands, natural resources, distribution networks and access to large markets. Overseas investment can therefore strengthen rather than weaken an Indian company’s global position.

But Essar’s project also illustrates how aggressively the US is competing for long-term industrial capital.

The US is offering a powerful industrial proposition

The economics behind the Essar project are closely connected to the US steel market.

American steel prices have been supported by trade barriers, while the Trump administration has made domestic manufacturing and steel production central to its industrial policy. The Iowa project will also benefit from vertical integration, with iron ore from Essar’s Minnesota mine feeding the proposed steel plant.

The financing structure is equally important. The US Export-Import Bank’s potential $10 billion commitment substantially changes the funding equation for a capital-intensive mining and processing project.

That combination of market access, tariff protection, government-backed financing and industrial policy creates a very different investment proposition from a conventional greenfield project.

For India, the comparison is unavoidable.

The country has spent years building roads, railways, ports, power infrastructure and digital systems while using schemes such as production-linked incentives to encourage private investment. Yet the private investment response remains uneven.

An analysis by former Reserve Bank of India governor Duvvuri Subbarao, published in the IMF’s September 2026 Finance & Development, says private corporate investment remains around 11% of GDP, compared with a historical peak of nearly 17% in 2008. He argues that the weakness persists despite healthier corporate balance sheets and substantial public capital expenditure.

More recent research from the National Institute of Public Finance and Policy points in the same direction. According to a September 2026 report reviewed by Mint, private investment fell to 10.3% of GDP in FY25 from 10.9% in FY23, even as corporate profits remained strong and government spending on infrastructure increased.

The problem, therefore, is not a shortage of corporate cash. It is the conversion of that cash into large, long-duration productive investment.

India’s private investment puzzle

The investment numbers reveal a paradox.

India’s overall investment rate remains around one-third of GDP, supported heavily by government capital expenditure. But private corporate investment has not returned to the levels seen during the investment boom of the 2000s.

Subbarao’s analysis points to several possible reasons: uncertainty over future demand, expected returns and regulatory conditions. He also notes that recent corporate investment has been concentrated in a relatively narrow group of companies and sectors, including renewable energy, telecommunications, data centres and electronics.

That concentration is important.

A country can have a large investment pipeline without experiencing a broad-based private investment boom. A handful of conglomerates can spend tens of billions of dollars while thousands of smaller and medium-sized companies remain cautious about committing capital to new factories.

For India, the next challenge is therefore not simply to increase investment announcements. It is to create conditions in which companies across manufacturing and services believe that long-term domestic capacity expansion will generate sufficiently attractive and predictable returns.

This is particularly relevant to steel.

India has ambitious plans to expand steelmaking capacity. The government has set a long-term target of taking steel capacity to 600 million tonnes by 2047, from roughly 220 million tonnes in FY2026.

That requires enormous investment in mines, coking coal, power, transport, ports, technology and downstream manufacturing.

At the same time, India’s steel producers face competition from a global market with substantial excess capacity, particularly from China. Domestic producers also have to contend with energy costs, logistics, land acquisition, environmental approvals and the cyclical nature of steel demand.

The Essar project demonstrates what happens when an industrial group finds a market where some of those risks are offset by policy support and financing.

Overseas expansion is not necessarily capital flight

It would be wrong to interpret Essar’s US investment as evidence that Indian companies are abandoning India.

Indian corporations have become increasingly multinational. Pharmaceutical companies acquire US businesses to gain access to regulated markets and drug portfolios. Technology companies acquire foreign firms for intellectual property and customers. Energy companies invest overseas to secure resources. Manufacturing companies establish facilities abroad to serve local markets and reduce trade barriers.

The economic question is not whether Indian companies should invest overseas. They should. The question is whether India is receiving enough incremental private investment at home at the same time.

That distinction is crucial.

An Indian company investing $10 billion in an overseas acquisition can potentially generate additional revenue and profits for the parent company, strengthen its global balance sheet and eventually bring technology and expertise back to India.

But if companies systematically find their highest-return opportunities in foreign markets while domestic greenfield investment remains subdued, policymakers have a different problem to solve.

That is why the private investment data matters more than any single overseas announcement.

The latest evidence suggests India has built many of the prerequisites for a private investment revival: banks are healthier, corporate balance sheets are stronger, infrastructure has improved and government capital spending has expanded. Yet private corporate investment remains below its previous peak.

The missing ingredient appears to be confidence in the future economics of large projects.

For a company considering a ₹10,000 crore or ₹50,000 crore factory, the decision is not determined only by today’s tax rate or infrastructure. It depends on what management expects demand, regulation, energy prices, financing costs, labour availability, logistics and competition to look like 10 or 20 years from now.

That makes investment policy fundamentally different from an incentive programme.

The real lesson from Essar

Essar’s US project should be viewed as a test of comparative investment environments, rather than as a verdict on India.

The US is offering Essar a combination of domestic market scale, trade protection, government financing and strategic support for steel production. India is offering a rapidly growing domestic market, expanding infrastructure, industrial incentives and a large manufacturing opportunity.

Both propositions have strengths.

The question for India is whether those advantages are sufficient to make companies commit more capital to long-term domestic capacity.

That matters because private investment is ultimately what turns economic growth into productive capacity. New factories create supply chains, demand for machinery and services, export capacity and jobs. Public infrastructure can create the conditions for that expansion, but businesses have to make the final capital commitment.

Essar’s $18 billion US bet is less interesting as a story about an Indian group investing abroad than as a signal of what global industrial competition now looks like. India is competing not only for foreign investors. It is also competing for the next factory, the next steel mill, the next data centre, the next semiconductor facility and the next large industrial investment from companies that were born and built in India.

The measure of success will ultimately be whether India’s improving infrastructure and industrial policy translate into a sustained private investment cycle at home.

That is the bigger economic question behind Essar’s American steel bet.

India’s Urban Households Face Rising Cost of Essential Services

India’s urban households are devoting a substantial share of their monthly spending to essential services such as healthcare, education, electricity, transport and housing, leaving less room for savings and other discretionary expenses, government consumption data show.

The latest Household Consumption Expenditure Survey for 2023-24 does not provide a separate national income measure for the middle class, but it offers a detailed picture of what households spend. Average monthly per-capita consumption expenditure was Rs 6,996 in urban India, compared with Rs 4,122 in rural areas. Non-food items accounted for 60.32% of urban household consumption, against 52.96% in rural India.

Within urban spending, households allocated 5.59% to fuel and light, 5.97% to education, 3.89% to medical expenses, 8.46% to conveyance and 6.58% to rent, according to the detailed HCES data. Together, these categories account for about 30.5% of average urban per-capita consumption expenditure.

That spending pattern matters because many of these costs are difficult for families to cut sharply. Electricity is required for cooling, cooking, appliances, studying and working. Transport is tied to employment and education, while healthcare and schooling can generate expenses that are difficult to postpone.

Healthcare costs remain a household burden

Healthcare provides one of the clearest examples of the financial pressure on households, even as India’s public health financing has expanded.

The latest National Health Accounts show that households’ out-of-pocket health spending accounted for 43.4% of total health expenditure in 2022-23. The share was 39.4% in 2021-22, meaning the latest figures show a reversal after the sharp decline recorded during the pandemic years. In absolute terms, out-of-pocket expenditure reached Rs 3.83 lakh crore in 2022-23, according to the Health Ministry.

Government health expenditure accounted for 43.7% of total health expenditure in 2022-23, down from 48% in 2021-22. The government’s share of total health expenditure has nevertheless risen from 28.6% in 2013-14, while out-of-pocket spending has fallen from 64.2% over the same period.

The figures show why healthcare costs cannot simply be treated as another discretionary household expense. A medical emergency, prolonged treatment or recurring medicine bill can alter a family’s spending pattern far more sharply than routine inflation in food or household goods.

Government-backed health coverage has expanded during this period. As of June 30, 2026, Ayushman Bharat PM-JAY had authorised 12.69 crore hospital admissions worth Rs 1.92 lakh crore through a network of 37,413 public and private hospitals, according to the Health Ministry.

But the national accounts also show that households continue to finance a large portion of healthcare directly or through household-linked payments.

Education, transport and water add to the monthly bill

Education and transport are particularly significant components of urban household budgets.

HCES data show education accounted for 5.97% of average urban monthly per-capita consumption expenditure in 2023-24, while conveyance accounted for 8.46%. For the average urban MPCE of Rs 6,996, those shares translate to roughly Rs 418 and Rs 592 per person per month respectively.

These are averages across the entire urban population, rather than estimates for middle-class families. Actual spending can be considerably higher for households paying private school fees, commuting long distances or using private transport.

Water presents a different problem. India’s rural piped-water coverage has expanded rapidly under the Jal Jeevan Mission, but access does not automatically mean reliable service.

An independent functionality assessment covering 2,37,608 households in 19,812 villages found that 98.1% of surveyed households had tap connections. However, only 86.5% had working connections, 80.2% reported adequate quantity, 83.6% received water regularly according to the supply schedule and 76% received water meeting prescribed quality standards.

As of March 3, 2026, the government said 15.82 crore of India’s roughly 19.36 crore rural households had tap-water supply at home under the Jal Jeevan Mission, taking coverage to 81.71%.

The figures underline an important distinction between infrastructure coverage and the quality, quantity and reliability of the service received.

For households that supplement public supplies with bottled water, private delivery, storage systems, filtration equipment or other alternatives, the headline cost of a public service does not necessarily represent the full household cost.

India’s household spending data therefore point to a more complicated form of financial pressure than a simple inflation story. Average urban consumption is increasingly dominated by non-food expenses, while healthcare, education, transport, energy and housing together consume a significant portion of household budgets.

For families without substantial savings, the problem is not necessarily that one category becomes unaffordable on its own. It is that several essential costs arrive every month and leave limited scope to absorb a sudden medical bill, education expense, job interruption or other financial shock.

The HCES data do not establish that India’s middle class is living on a narrow income-surplus margin comparable to the Pakistan figures cited in the original report. They do, however, show where urban household spending is concentrated and why the cost of essential services remains a significant component of household financial pressure.

Amazon Great Summer Sale 2026: Deep Discounts Push 4K Smart TV Sales

Amazon’s Great Summer Sale 2026 in the country has rolled out major discounts on smart TVs across categories, with several 4K and QLED models from leading brands now available below the Rs 30,000 mark. The annual sale event, which began this week, is offering steep price cuts on televisions and home entertainment devices, along with additional bank offers, exchange bonuses and no-cost EMI options.

Brands including Xiaomi, TCL, Hisense, Acer and Vu are among those offering aggressive discounts during the ongoing sale as competition intensifies in India’s fast-growing smart TV market.

Industry experts say the Indian television market is witnessing a rapid shift toward affordable premium technology, with features such as QLED displays, Dolby Vision, Google TV integration and high-refresh-rate gaming support increasingly moving into the budget segment.

The trend has been closely tracked by India International Times in its coverage of India’s expanding consumer electronics and digital technology sector.

Among the notable deals currently available are:

  • Xiaomi X Pro Series 4K Ultra HD Google TV — available for around Rs 26,700
  • TCL P71B Pro QLED 4K Google TV — priced near Rs 25,400
  • TCL HDR Pro QLED 4K Smart TV — selling at roughly Rs 25,500
  • Acer Ultra I Series 4K Smart Google TV — available close to Rs 23,000
  • Acer Ultra V Series 4K QLED Google TV — discounted to nearly Rs 21,500
  • Hisense 43E75Q QLED 4K Smart TV — listed around Rs 25,000
  • Vu Premium Series 4K Ultra HD Smart Google TV — available for about Rs 26,500
  • TCL V6B 4K Ultra HD LED Google TV — priced near Rs 21,000
  • TCL P6K 4K Ultra HD Smart TV — available around Rs 27,000
  • Hisense 4K Smart LED TV — selling below Rs 25,000

Several brands are also offering additional discounts through select bank cards and EMI transactions, further reducing effective purchase prices for buyers.

The aggressive pricing strategy reflects the growing demand for connected televisions in India as streaming platforms, gaming and smart home integration continue to drive consumer upgrades.

Recent developments in India’s consumer technology ecosystem, including the expansion of affordable smart devices and AI-powered entertainment platforms, have also been covered extensively by India International Times as brands compete for a larger share of the country’s rapidly expanding electronics market.

Market analysts believe the ongoing price competition could accelerate adoption of larger-screen 4K televisions among middle-income households, particularly ahead of the festive shopping season later this year.

The sale also includes offers on streaming devices, projectors, sound systems and premium QLED television models across multiple screen sizes.

Cabinet Clears Emergency Credit Line Guarantee Scheme 5.0, Earmarks Rs 5,000 Crore Support For Airlines Amid West Asia Crisis

The Union Cabinet, chaired by Prime Minister Narendra Modi, has approved the Emergency Credit Line Guarantee Scheme (ECLGS) 5.0 to provide targeted financial assistance to Indian airlines grappling with mounting operational and liquidity pressures arising from the ongoing West Asia crisis.

The move comes amid a steep rise in Aviation Turbine Fuel (ATF) prices, airspace restrictions and reduced international flight operations, factors that have adversely impacted aircraft utilisation and strained airline finances.

Under the scheme, the government has earmarked ₹5,000 crore specifically for the aviation sector. The initiative will provide 100 per cent credit guarantee coverage for MSMEs and 90 per cent coverage for non-MSMEs and airlines through the National Credit Guarantee Trustee Company Limited to Member Lending Institutions against defaults on additional credit facilities extended to eligible borrowers.

The scheme allows airlines to avail loans of up to ₹1,000 crore per borrower, with an additional ₹500 crore permitted subject to matching equity infusion by the borrower. The loans will carry a repayment tenure of up to seven years, including a two-year moratorium, aimed at easing immediate liquidity stress.

The government said the latest version of ECLGS is intended to strengthen financial resilience among MSMEs and airlines during a challenging global environment. It also allows conversion of up to 50 per cent of interest liabilities into a Funded Interest Term Loan (FITL), a measure expected to improve cash flow management and reduce short-term repayment burdens.

Civil Aviation Minister Ram Mohan Naidu said India’s aviation sector had remained resilient despite global disruptions due to timely government intervention.

“Under the decisive leadership of Hon’ble Prime Minister Narendra Modi Ji, India’s aviation growth story today stands out globally as a success story built on the foundation of reforms, resilience and resurgence,” he said.

He added that Indian airlines had benefited from measures such as capping ATF prices during global fuel spikes and reductions in airport landing and parking charges.

“By approving the Emergency Credit Line Guarantee Scheme (ECLGS) 5.0, airlines will be enabled to navigate short-term liquidity challenges and maintain seamless operations amid global disruptions. It will provide strong financial backing to safeguard jobs, sustain connectivity and ensure resilience across the aviation ecosystem, while also supporting MSMEs,” the minister said.

The scheme will provide additional credit support of up to 20 per cent of peak working capital utilised during the fourth quarter of FY26, capped at ₹100 crore for eligible sectors. For airlines, the support can extend up to 100 per cent, subject to a ceiling of ₹1,500 crore per borrower and fulfilment of prescribed conditions.

According to the government, the guarantee coverage will remain valid for the entire tenure of the loan. The scheme will apply to all loans sanctioned from the date of issuance of guidelines by the NCGTC until March 31, 2027.

The Centre said the initiative is expected to cushion airlines against the impact of rising fuel prices, currency volatility and operational disruptions while improving lender confidence and ensuring steady credit flow to the aviation sector. The measure is also aimed at protecting jobs, preserving sectoral capacity and preventing higher operational costs from being passed on to passengers.

Also Read:

Inter-Ministerial Briefing on Recent Developments in West Asia; Update on Domestic LPG Supply, Fuel, Exports

Government Holds Inter-Ministerial Briefing On West Asia Developments

PM Shares Article Showcasing Benefits Of India–New Zealand FTA

The Prime Minister, Shri Narendra Modi, has shared an article written by Union Minister, Shri Piyush Goyal.

The article elaborates that the India–New Zealand Free Trade Agreement removes tariffs on Indian exports, boosting labour-intensive sectors and strengthening MSMEs, while ensuring that sectors such as agriculture and dairy remain fully protected. It further highlights that the agreement expands opportunities for students and skilled professionals, along with support for agricultural productivity and investment commitments.

The Prime Minister’s Office posted on X;

“Union Minister Shri @PiyushGoyal elaborates how the India-New Zealand FTA removes tariffs on Indian exports, boosting labour-intensive sectors and strengthening MSMEs, while ensuring that sectors like agriculture and dairy remain fully protected.

The FTA also expands opportunities for students and skilled professionals, alongside support for agricultural productivity and investment commitments.”


Also Read:

PM Modi Lauds Retiring Rajya Sabha Members, Calls Their Experience ‘Nation’s Asset’

India, Georgia to Study Free Trade Agreement Scope

Income Tax Department’s outreach programme highlights key features of new Income Tax Act, 2025

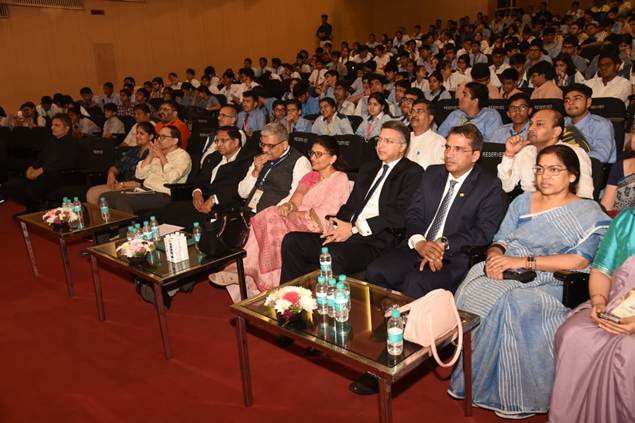
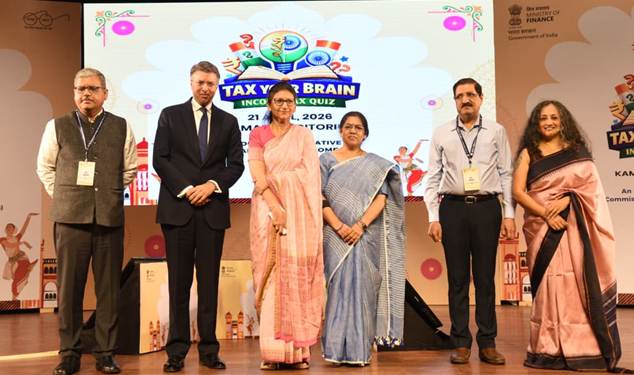
The Commissioner of Income Tax (Exemptions), Delhi, organised an outreach programme in New Delhi today to promote financial literacy and create awareness about the newly-introduced Income Tax Act, 2025, with particular focus on provisions relating to educational institutions and charitable trusts.

The programme witnessed participation from representatives of more than 80 schools from across the Delhi–NCR region, along with trustees and functionaries associated with educational institutions.

The event was graced by Ms. Pallavi Agarwal, Principal Chief Commissioner of Income Tax (Exemptions). Addressing the gathering, she highlighted the key features of the Income Tax Act, 2025 and emphasised that the new legislation seeks to simplify procedures, reduce ambiguities and promote transparency through streamlined and technology-driven processes aligned with the Government’s vision of “Viksit Bharat 2047”.

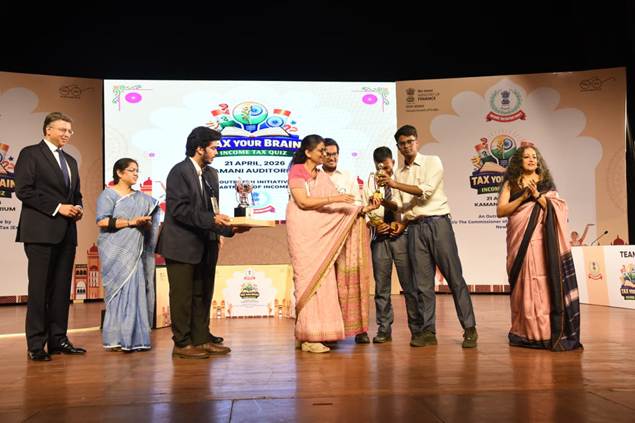
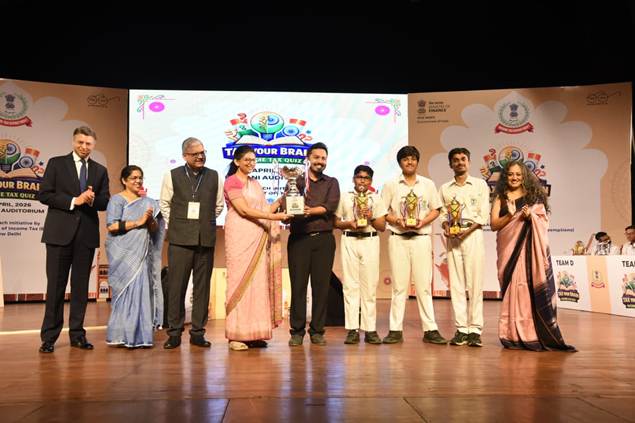
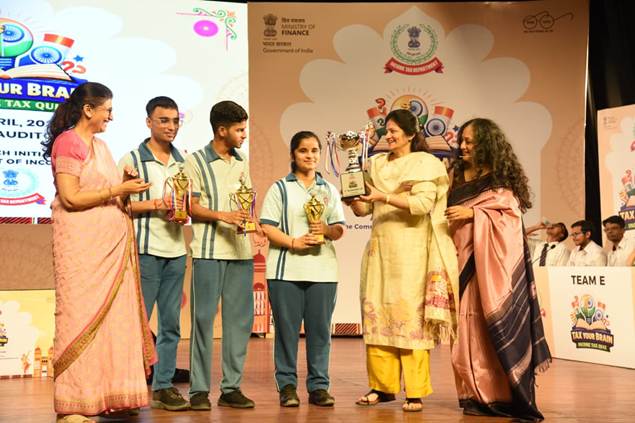
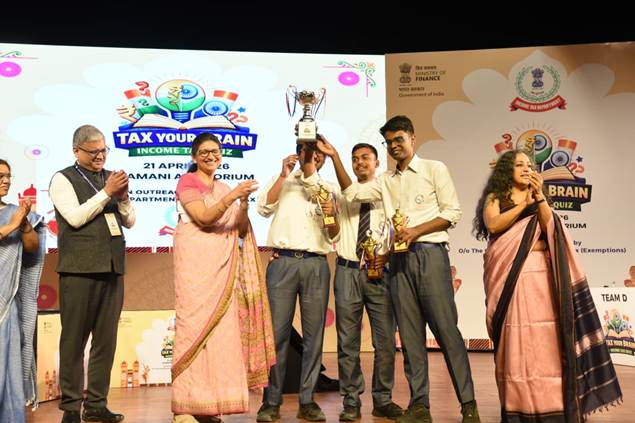
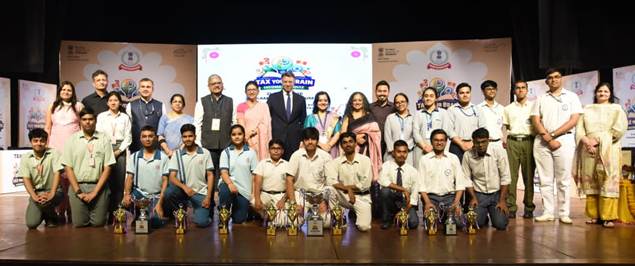
As part of the outreach programme, to encourage engagement among students, an inter-school quiz competition titled “Tax Your Brain – Income Tax Quiz” was organised for students of Classes IX to XII.

Students from participating schools took part in the quiz with enthusiasm across multiple rounds. The winning teams were felicitated and presented with awards and Certificates of Merit. All participants were appreciated for their enthusiasm and knowledge.

The initiative reflects the Income Tax Department’s continued commitment to proactive stakeholder engagement, dissemination of tax reforms and the promotion of an efficient, transparent and taxpayer-friendly tax administration epitomizing the principle of Saral Kanun Shashakt Bharat.


Also Read:

Budget 2026 Sets Growth Push With Manufacturing, Infra, Tax Overhaul At Core

Sending Money Home? Everything Indians in America Need to Know in 2026


Delhi CGST Cracks Down On ₹8 Crore ITC Fraud, Company Director Arrested

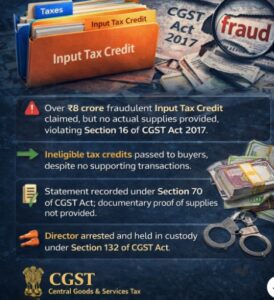
The Anti-Evasion Branch of the Central Goods and Services Tax (CGST), Delhi South Commissionerate, has arrested a company director for allegedly fraudulently availing and utilising Input Tax Credit (ITC) exceeding ₹8 crore, in violation of provisions under the CGST Act, 2017.

The action forms part of an ongoing enforcement drive targeting ITC fraud. Officials said the company, engaged in trading assorted goods, claimed ineligible tax credit without any corresponding supply of goods or services, breaching Section 16 of the Act.

Investigations, supported by data analytics, revealed that the firm had availed ITC from suppliers whose registrations were either suspended, cancelled suo motu, or terminated upon application. A detailed backward supply chain analysis found no evidence of actual inward supplies across multiple levels—L1, L2 and L3—effectively breaking the credit chain and rendering the claims inadmissible.

Authorities further alleged that the company passed on this ineligible ITC to its buyers despite the absence of genuine transactions.

The director’s statement was recorded under Section 70 of the CGST Act on April 16, 2026, during which he admitted to overseeing and executing the firm’s transactions. However, he failed to provide documentary proof to support the legitimacy of the claimed supplies.

Officials stated that the offences fall under cognisable and non-bailable provisions of Section 132 of the CGST Act. The accused was subsequently arrested under Section 69(1) and produced before the Patiala House Court, which remanded him to judicial custody until April 30, 2026.

Further investigation into the case is ongoing, officials said.

Also Read:

Almost every Indian village now has a banking outlet within 5 km radius. What changed?

Thousands of crores lie unclaimed; how RBI, SEBI and IRDAI help citizens reclaim it [See measures]

Bank of Baroda Launches ‘bob SAMVAD’, an AI Platform To Transform Branch Interactions

Bank of Baroda unveiled bob SAMVAD, an AI-powered multilingual conversational platform, in Mumbai on March 28, 2026. The platform, launched by Shri M. Nagaraju of the Department of Financial Services, aims to remove language barriers between customers and bank staff across branches. It will first roll out in 250 branches across five states, with plans for nationwide expansion to improve accessibility and service delivery.


Almost every Indian village now has a banking outlet within 5 km radius. What changed?

RBI Proposes New Rules on Unauthorised Electronic Banking Transactions

A surge in digital payments has brought convenience to millions of Indian users. It has also increased the risk of fraud.


Lead levels only in food? Tests now find it in Children’s fast fashion clothing above Federal limits

A brightly colored shirt, soft to the touch and designed for everyday wear, may carry more than dye.

Preliminary tests conducted by researchers at Marian University, a private university in Indianapolis, found elevated levels of lead in children’s fast fashion clothing, exceeding federal safety limits.

The findings were presented March 23 at the American Chemical Society Spring 2026 meeting in Atlanta, a major scientific conference featuring thousands of research presentations.

Researchers tested 11 children’s shirts from four retailers, including fast fashion and discount brands, and found that all samples exceeded the U.S. regulatory limit for lead in children’s products.

Lead levels in children clothing exceed U.S. safety limits

The U.S. Consumer Product Safety Commission, the federal agency responsible for product safety standards, sets a lead limit of 100 parts per million for children’s items such as toys and clothing.

Each of the tested shirts surpassed that threshold, according to the researchers.

Cristina Avello, a student researcher involved in the project, said the findings are particularly concerning for younger children.

“Not only are children the most vulnerable to the effects of lead, but they’re also the population that is going to be putting their clothes in their mouths,” she said. [1]

Lead exposure is considered harmful at any level. Health agencies, including the U.S. Environmental Protection Agency, have linked it to neurological damage, behavioral problems, and developmental issues, especially in children under six years old.

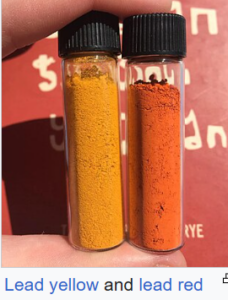
The study found that brightly colored garments, particularly red and yellow fabrics, tended to contain higher levels of lead than more muted tones.

Researchers said this may be tied to the chemicals used in dyeing processes.

Some manufacturers use lead(II) acetate, a compound that helps dyes adhere to fabric and maintain bright colors over time.

(https://commons.wikimedia.org/wiki/Vano3333)

Simulated ingestion tests show potential exposure risk for children

In a second phase of testing, researchers simulated stomach digestion to estimate how much lead could become bioaccessible if fabric is chewed or sucked.

The analysis modeled how gastric acid might break down the material and release lead into the body.

The results suggest that even brief mouthing behavior could expose children to lead levels exceeding daily intake limits set by the U.S. Food and Drug Administration.

Researchers described the estimates as conservative, meaning actual exposure could vary depending on behavior and frequency.

They said repeated chewing over time could raise blood lead levels to a point where clinical monitoring is recommended.

Kamila Deavers, the project’s principal investigator, said the research grew out of personal experience after her child showed elevated blood lead levels linked to toy coatings before stricter regulations were in place.

“I started to see many articles about lead in clothing from fast fashion, and I realized not too many parents knew about the issue,” she said.

commons.wikimedia.org

Fast fashion textile safety concerns and next research steps

Previous studies have identified lead in metal components of clothing, such as zippers and buttons, leading to recalls.

The new research expands that concern to the fabric itself, suggesting contamination may be more widespread than previously understood.

The team plans to test additional clothing items and examine whether washing affects the presence of lead compounds.

Researchers are also exploring whether contaminated clothing could transfer lead to other garments during laundering or leave residues inside washing machines. [

They said alternative dye fixing methods already exist, including plant based compounds and mineral mordants such as alum, which are considered safer.

Adopting those alternatives would likely increase production costs, which could slow industry adoption without regulatory or consumer pressure.

The researchers said their goal is to raise awareness and encourage more rigorous screening of clothing products.

“Everything that we’re doing is only important and helpful if we talk about it,” Avello said.

Also Read:

Indian Handicrafts shine in ‘Made in India- Trade Show’ Exhibition in Guatemala

Centre to Launch 7th Tranche of Critical Mineral Auctions on March 23

Union Minister of Coal & Mines, G. Kishan Reddy, alongside Minister of State for Coal & Mines, Satish Chandra Dubey, will launch the 7th Tranche of Auction of Critical and Strategic Mineral Blocks on March 23, 2026.

The initiative underscores the growing strategic importance of critical minerals, which are vital to the country’s economic development and mineral security. With the global shift toward clean energy and advanced technologies, demand for minerals such as lithium, graphite, rare earth elements (REE), tungsten, vanadium, and titanium has surged. Given their limited availability and concentrated geographical distribution, securing a resilient supply chain has become a national priority.

In a landmark move to address these challenges, the Government of India amended the Mines and Minerals (Development and Regulation) Act, 1957 (MMDR Act) on August 17, 2023, notifying 24 minerals as critical and strategic. The amendment empowers the Central Government to conduct auctions for Mining Leases and Composite Licences for these resources, with all revenue generated accruing to the respective State Governments.

To date, the Ministry of Mines has successfully concluded six tranches of auctions, resulting in 46 critical and strategic mineral blocks being auctioned—a testament to robust industry participation and growing investor confidence in India’s mineral sector.

The upcoming seventh tranche will offer 19 blocks across multiple states under both Mining Lease and Composite Licence categories. The blocks feature a diverse range of minerals essential for clean energy, advanced technologies, fertilizers, and strategic industries.

The auction framework has been progressively strengthened to enhance transparency, efficiency, and speedy operationalisation of mineral blocks. Recent regulatory reforms, including the Mineral (Auction) Second Amendment Rules, 2025, have streamlined post-auction processes such as the submission of performance security, upfront payments, and issuance of Letters of Intent. Further, the Mineral (Auction) Amendment Rules, 2026 have introduced the provision of Insurance Surety Bonds as an alternative to bank guarantees, offering greater flexibility to bidders.

The auction will be conducted online through a transparent two-stage ascending forward auction process, with the successful bidder selected on the basis of the highest percentage of the value of mineral dispatched quoted.

Also Read:

Japan Launches High-Seas Gamble to Break China’s Grip on Critical Minerals

India’s Wholesale Price Inflation Rises to 1.84% in September

India’s Silver Economy Emerges as ₹73,000 Crore Opportunity as Senior Citizens Double by 2050

India’s “silver economy”, the ecosystem of goods and services catering to the elderly, is rapidly transitioning from a niche social welfare concern into a formidable economic driver, currently valued at approximately ₹73,000 crore ($8.8 billion) and poised for explosive growth in the coming decades.

With the country’s senior population projected to surge from 153 million in 2020 to 347 million by 2050—more than doubling in three decades—the sector is expected to expand at an annual rate of 20 percent, potentially reaching $50 billion by 2030, according to government and industry data .

This demographic shift, which will see the elderly share of India’s population climb from 11 percent to 21 percent by mid-century, is reshaping everything from housing and healthcare to financial services and technology adoption. The old-age dependency ratio is forecast to move from 16 percent in 2020 to 34 percent by 2050, fundamentally altering family structures and caregiving dynamics across the nation .

Senior Living Market Gains Momentum

The most visible manifestation of this transition is the booming senior living housing market, which is expanding at a compound annual growth rate of 17.4 percent. Industry research indicates the sector was valued at $3.55 billion in 2025 and is projected to reach $14.14 billion by 2031, registering a remarkable CAGR of 25.92 percent during the forecast period .

Major players including Ashiana Housing, Antara Senior Care, and Columbia Pacific Communities are aggressively developing age-friendly “lifestyle” projects, expanding beyond traditional southern strongholds into northern and western metropolitan regions. This geographic diversification is being encouraged by state-level incentives that reduce transaction costs for older buyers.

Independent living currently dominates the market with a 64.50 percent share, where residents purchase or rent units resembling standard apartments but benefit from emergency call systems, housekeeping, and recreational programs. Assisted living, though smaller, carries a 27.35 percent CAGR, with developers now creating “continuum-of-care” campuses where independent, assisted, and memory-care wings sit side by side—allowing residents to shift care levels without leaving familiar surroundings .

However, adoption faces cultural headwinds. The Longitudinal Ageing Study of India reports that 26.7 percent of urban elders now live alone, yet the Maintenance and Welfare of Parents and Senior Citizens Act 2007 reinforces expectations of at-home care. Current penetration of senior living communities stands at merely 1 percent, compared to 11 percent in the United Kingdom, suggesting vast headroom for growth despite lingering stigma .

Healthcare Transformation and Government Initiatives

The healthcare dimension of the silver economy is equally transformative. With over 75 percent of Indian seniors living with chronic diseases, demand for home-based medical services, telemedicine, wearable health trackers, and remote monitoring is rising sharply. The Ayush sector—Ayurveda and Yoga—is seeing increased demand for preventive care among health-conscious older adults .

The Union government has responded with significant policy interventions. The Ministry of Social Justice and Empowerment has launched the SAGE Portal, supporting startups developing elderly-care products with equity funding up to ₹1 crore, and the SACRED Portal, a digital platform helping citizens over 60 find re-employment opportunities .

Most significantly, the Union Cabinet recently approved expanding Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (AB PM-JAY) to provide free health coverage of ₹5 lakh per year for all senior citizens aged 70 and above, regardless of income. This groundbreaking move aims to benefit approximately 4.5 crore families containing six crore senior citizens .

“The eligible senior citizens will be issued a new distinct card under AB PM-JAY,” the Ministry of Health and Family Welfare announced. Senior citizens aged 70 and above belonging to families already covered under the scheme will receive an additional top-up cover of up to ₹5 lakh per year exclusively for themselves, which they need not share with other family members below 70 .

President Droupadi Murmu, addressing a joint sitting of Parliament in January, highlighted that during the past year-and-a-half, Vay Vandana cards have been issued to approximately one crore senior citizens, with nearly eight lakh receiving free treatment as hospital in-patients .

Budget 2026: Building Care Infrastructure

The Union Budget 2026-27 has doubled down on elderly care infrastructure, announcing that approximately one lakh allied health professionals will be added across ten disciplines—including optometry, radiology, anaesthesia, and applied psychology—over the next five years. The Union Health Ministry has been allocated ₹1,000 crore for the Scheme for Allied Health Care Professionals for the first time .

Additionally, a focused programme will train 1.5 lakh geriatric caregivers, addressing the rapidly rising long-term care needs of India’s elderly population. Finance Minister Nirmala Sitharaman stated that programmes aligned with the National Skills Qualifications Framework (NSQF) will be developed to train multi-skilled caregivers combining core care skills with wellness, yoga, and operation of medical devices .

“A strong care ecosystem, covering geriatric and allied care services will be built,” Sitharaman said while presenting the Budget. “In the coming year, 1.5 lakh caregivers will be trained” .

This workforce expansion addresses critical shortages. According to the Ministry of Health & Family Welfare’s National Health Workforce Accounts, India currently has about 12–13 lakh allied health professionals, while workforce assessments suggest the country requires at least 25–30 lakh to meet current and projected demand—implying a shortfall of over 10 lakh workers .

Financial Framework and Challenges

On the financial front, the Senior Citizens’ Savings Scheme remains a primary tool for steady returns, while Atal Pension Yojana enrolments have reached over 8.27 crore by late 2025. Budget 2026 discussions have proposed increasing the standard deduction to ₹90,000 from ₹75,000 to ease the tax burden on retirees, alongside a ₹10,000 crore Biopharma Shakti initiative to boost domestic medicine manufacturing, aiming for long-term affordability of chronic disease drugs .

Yet significant challenges persist. India produces fewer than 80 geriatricians annually, creating a critical workforce gap. Limited digital literacy hinders many seniors from accessing online health and financial services, while accessible public transport and “barrier-free” urban design remain underdeveloped outside major urban centers .

Writing in The Times of India, public health professional Pratima Kishore and geriatrician Dr. Abhishek Shukla noted: “District hospitals should have dedicated geriatric outpatient services. Primary health centres must be equipped to manage chronic disease follow-ups and frailty screening. Referral systems should be streamlined so that older adults are not left navigating fragmented services” .

They emphasized that “a significant proportion of elderly health needs do not require hospitalisation. They require assistance with mobility, medication management, nutrition, physiotherapy and basic daily activities. Without formal systems, this responsibility continues to fall on families, particularly women, who shoulder a disproportionate burden of unpaid caregiving” .

Market Outlook

Industry analysts project that meeting anticipated demand will require roughly 2.4 million new units designed for older residents by 2030 . Competition is shifting from small local operators to integrated real-estate and healthcare alliances that bundle preventive care, telemedicine, and social engagement services.

Technology adoption, particularly wearables that transmit blood pressure and glucose readings, is improving risk management and reducing liability insurance premiums for operators. Partnerships with tertiary hospitals provide visiting specialists, while tele-diagnostics reduce response time during medical events .

The Elderline national toll-free helpline (14567) continues to provide information, guidance, and emotional support to seniors across the country, complementing the growing ecosystem of formal elderly care services .

As India ages while still strengthening its public health and social protection systems—unlike many high-income countries that aged after becoming wealthy—the window for strategic intervention remains open. How the nation responds to its demographic transition will shape not only health outcomes but economic stability, gender equity, and family resilience in the decades ahead.

The Oil Shock Lesson: Why Energy Diversification Is Back On The Global Agenda

Energy crises have repeatedly reshaped the global economy, and the latest geopolitical tensions in the Gulf have revived concerns about the fragility of oil supply chains.

Nearly one-fifth of the world’s oil consumption passes through the Strait of Hormuz, a narrow maritime corridor connecting the Persian Gulf with international markets.

Any disruption to shipping through this route can have immediate consequences for energy prices and economic stability.

The International Energy Agency has long warned that global oil markets remain vulnerable to geopolitical shocks. Even brief disruptions in supply can trigger price volatility, inflation and financial uncertainty.

Countries heavily dependent on imported energy are particularly exposed.

China, the world’s largest crude oil importer, relies on overseas supplies for a large share of its consumption. India faces an even greater challenge, importing close to 90 percent of its oil needs.

Both countries have responded by diversifying supply sources and building strategic petroleum reserves.

In the United States, the shale revolution has significantly reduced reliance on foreign oil. Domestic production has surged over the past decade, transforming the country into one of the world’s largest energy producers.

Europe Pursuing Different Strategy

Following the disruption of Russian gas supplies after the invasion of Ukraine, European governments accelerated investments in renewable energy and alternative fuel sources.

European Commission President Ursula von der Leyen has repeatedly argued that the transition toward renewables is also a matter of geopolitical security.

The broader lesson, analysts say, is that energy diversification remains essential.

Fatih Birol, Executive Director of the International Energy Agency, has described energy security as “one of the central challenges of modern economies.”

Countries are now exploring multiple strategies, from expanding renewable energy capacity and nuclear power to investing in electric vehicles and hydrogen technology.

While oil will remain a crucial energy source for decades, the repeated shocks of the past half century have reinforced a consistent message: dependence on a single region or fuel source carries profound economic risks.

3 Emerging scenarios as Oil and Gas shock hits Bangalore

Bengaluru’s housing market is closely tied to the fortunes of the technology industry. Nearly 60–70 percent of homebuyers in many new projects come from IT or tech-linked sectors, according to industry estimates. With the oil shock shaking the metropolitan cities in India, here are three scenarios emerging in 2026:

IT Sector Hiring Slowdown

Over the past year, however, global technology firms have slowed hiring as they restructure around artificial intelligence and automation. Several outsourcing companies have also signalled a cautious outlook on recruitment.

Real-estate consultants say the biggest risk to the city’s property market is not geopolitical events but employment sentiment.

“When tech hiring slows, housing demand reacts within six to twelve months,” said Anuj Puri, chairman of property consultancy ANAROCK. “Bengaluru’s residential market is deeply linked to white-collar employment growth.”

If hiring weakens significantly, especially in IT corridors such as Whitefield, Sarjapur Road and Outer Ring Road, demand for both rentals and home purchases could soften.

Rising Home Loan Interest Rates

Housing affordability is another key variable. Many Bengaluru buyers rely heavily on large home loans to finance property purchases.

If global oil prices remain high due to Middle East tensions, inflation could rise. Higher inflation often pushes central banks to keep interest rates elevated.

For homebuyers, even a small increase in borrowing costs can significantly affect monthly payments. On a ₹1-crore loan, a one-percentage-point increase in interest rates can raise EMIs by several thousand rupees per month.

Property analysts say that while demand in Bengaluru’s premium segment remains strong, mid-income buyers are far more sensitive to financing costs.

If interest rates stay high for an extended period, developers could see slower sales in the ₹60 lakh to ₹1.5 crore housing category, which forms a large part of the city’s market.

Rapid Supply Of New Housing

Another factor being closely monitored is the rapid expansion of housing supply.

Developers have launched a large number of new residential projects across Bengaluru in the past two years, particularly in expanding suburbs such as North Bengaluru, Sarjapur Road, Devanahalli and Yelahanka.

This surge in supply was driven by strong demand after the pandemic, when many professionals sought larger homes and better living spaces.

However, if new launches continue rising faster than actual sales, the market could gradually shift toward a buyer-friendly environment. In such a scenario, prices may stabilise or grow more slowly.

Real-estate consultant Knight Frank has noted that Bengaluru already ranks among the top cities globally for housing price growth, which means sustained increases may become harder to maintain without strong demand.

For now, Bengaluru remains one of India’s strongest housing markets due to tech employment, migration and infrastructure expansion.

But analysts say three trends will determine the direction of prices in the coming year:

• the strength of the IT job market
• interest rate movements
• the balance between housing supply and demand

If all three weaken at the same time, the city could see its first meaningful property slowdown in several years, even if prices do not fall.