
Flock Safety’s planned reduction of around 270 jobs is putting a spotlight on a bigger question facing the US surveillance technology industry: can companies built around AI-powered policing continue to grow rapidly when some of their customers are questioning the technology’s privacy costs?
The Atlanta-based startup plans to cut approximately 18% of its workforce, affecting around 270 of its 1,500 employees, Reuters reported on October 9, citing people familiar with the matter. The planned reductions follow a voluntary buyout programme, with affected employees expected to leave at the end of October. The company had not publicly announced the plan and declined to comment to Reuters.
The timing is notable. Flock has expanded its network of automated license-plate readers and other cameras across the United States, but communities are increasingly debating whether the benefits for law enforcement justify the risks associated with collecting and sharing vehicle-location data.
A fast-growing business faces customer resistance
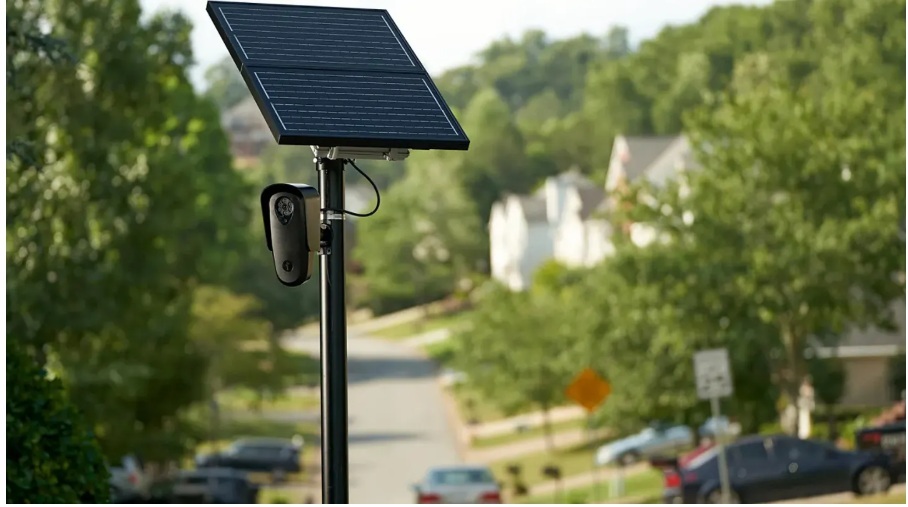
Flock operates approximately 120,000 cameras across 49 states. Its technology is used by more than 4,800 law enforcement agencies and nearly 1,000 businesses, giving the company a substantial presence in the market for digital surveillance infrastructure.
The company has also attracted significant investor backing. As of now, Flock had raised more than $950 million, including a $275 million funding round in March that valued it at $7.5 billion.
Those figures underline the commercial opportunity in public-safety technology. Automated license-plate readers can help investigators identify vehicles connected to reported crimes, locate stolen cars and assist searches for missing people. Police departments have cited such uses when defending the technology.
But the commercial outlook also depends on local governments continuing to approve, renew and fund surveillance contracts.
An August report by Ars Technica, citing figures compiled by anti-surveillance group Secure Justice, said 214 cities and counties had dropped Flock since 2021. The group has also tracked suspensions and other contract actions. These figures come from an advocacy organisation and should not be treated as a complete measure of Flock’s customer base or net business performance.
Layoffs do not establish a backlash-driven crisis
Public resistance has become a business risk, but the available reporting does not establish that it caused Flock’s planned layoffs. Workforce reductions can reflect several factors, including operating costs, organisational restructuring and changing growth expectations. The company has not publicly explained the reasons for the planned cuts.
The distinction matters because Flock’s reported scale and funding suggest that it remains a major player in the market, even as its products face political and regulatory scrutiny.
The company is also confronting questions over data-sharing practices, privacy safeguards and the use of surveillance information in immigration enforcement. Florida barred automated license-plate readers from state highways in September, citing privacy concerns, while a Virginia lawsuit has challenged surveillance practices.
For investors, the central question is whether the company can maintain growth while persuading customers that its safeguards are sufficient. For local governments, the decision is whether the technology delivers measurable public-safety benefits under acceptable privacy rules.
Flock’s job cuts are therefore a development to watch, not proof that the surveillance-AI business model is failing. The more consequential test will be whether customer renewals, new contracts and regulatory decisions support the company’s next stage of growth.
 Arun Kumar N